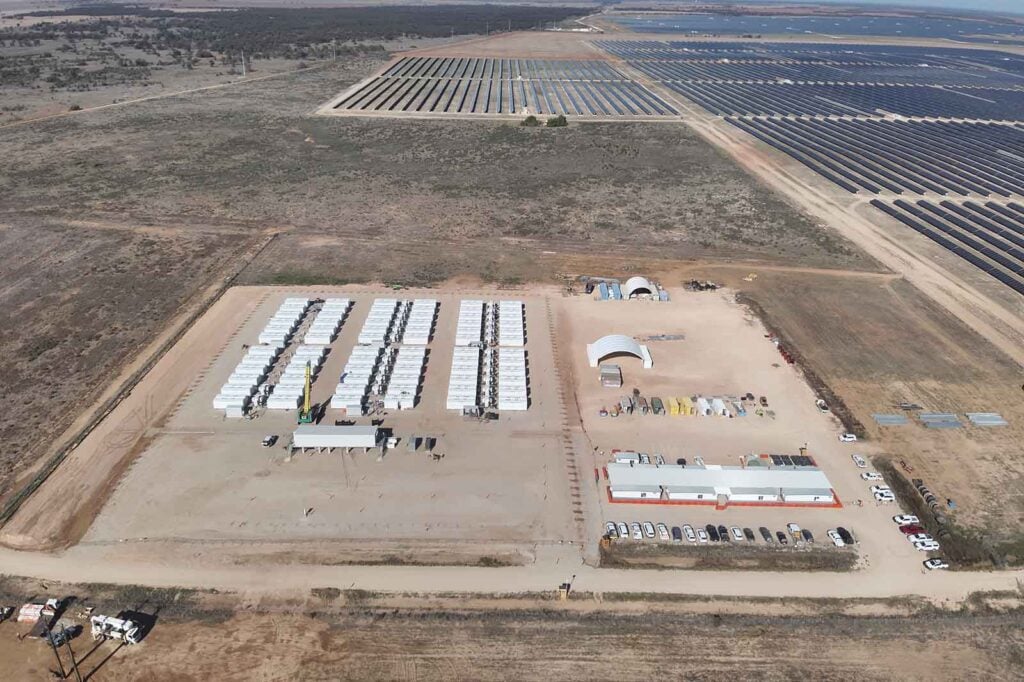
Australia’s 59 grid-scale battery energy storage systems (BESS) earned a combined AU$88.91 million (US$61.99 million) in estimated gross energy and Frequency Control Ancillary Services (FCAS) market revenue in the National Electricity Market (NEM).
This was during the third quarter of 2026, up 57% on the AU$56.74 million recorded in the second quarter.
The figures come from NEMPulse, a platform that tracks battery storage dispatch and revenue across the NEM using publicly available Australian Energy Market Operator (AEMO) data.
Normalised across the fleet’s 9,342MW and 21,544MWh of active systems, BESS earned AU$9,517 per MW and AU$4,127 per MWh over the quarter, equivalent to roughly AU$38,000 per MW annualised.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
Per MW per day, a measure that strips out both fleet growth and the length of the reporting window, earnings rose 34% to AU$103.
Energy arbitrage accounted for 97% of total revenue, with FCAS contributing 2% and estimated Frequency Performance Payments the remaining 1%, for a total of AU$526,000.
Within FCAS, regulation services accounted for 62% of that segment and contingency services 38%, with regulation the single largest individual market at AU$899,000.
The fleet’s optimal capture rate, the share of available revenue actually earned relative to a perfect-foresight trading benchmark, improved by 9% over the quarter, from 45% to 54%. However, this still left an estimated AU$70.59 million unrealised against that theoretical ceiling.
NEMPulse separately modelled performance using AEMO’s published PREDISPATCH price forecasts rather than hindsight, finding that the fleet could have captured 69% of the perfect-foresight benchmark using only public price information, compared with the 52% actually realised across the 92 forecast-covered days in the period.
The firm described that figure as a reference point rather than a floor, since real dispatch decisions can outperform or underperform it depending on strategy, contracting and network constraints.
Performance varied sharply by individual asset. The Limondale Battery led on energy capture at 78%, followed by Supernode BESS and Swanbank BESS at 77% each. At the same time, Stanwell BESS, Eraring BESS 2 and Summerfield BESS 2 recorded negative capture figures of -56%, -59% and -71% respectively.
NEMPulse noted that low or negative capture reflects contracting structures and operational constraints as much as trading performance, rather than being automatic evidence of underperformance.
Revenue per MW also varied by battery duration class, with 4-hour-plus systems earning AU$22,000/MW over the quarter, well ahead of 2-hour systems at AU$8,118/MW, 1-hour systems at AU$4,818/MW and 3-hour systems at AU$2,418/MW, underlining the premium longer-duration assets continue to command in energy arbitrage.
The top three individual earners for the quarter were Eraring BESS at AU$8.82 million, Orana BESS at AU$7.62 million and Supernode BESS at AU$6.53 million.
Queensland led all regions on total revenue at AU$32.45 million across 14 BESS, followed by New South Wales at AU$28.12 million across 16 battery storage systems, Victoria at AU$19.87 million across 15 BESS and South Australia at AU$8.47 million across 14 BESS.
Revenue generation remained concentrated on a small number of high-value trading days, with five of the quarter’s 92 days accounting for 15% of total fleet earnings.
The strongest single day was 8 July, when the fleet earned AU$4.49 million, with Rangebank BESS recording the best individual battery-day performance at AU$683,000.
NEMPulse recorded 55 significant price events during the quarter, including the sharpest and most extreme pricing episode in Tasmania, which peaked at AU$23,200/MWh.
Williamsdale BESS earned its first market revenue during the period, adding 250MW of new earning capacity to the fleet.
Narrowing spreads reshaping contracts and return expectations
The quarter’s improved capture rate arrives against a backdrop of compressed trading conditions that panellists at the Battery Asset Management Summit Australia 2026 in Sydney in August described as a genuine squeeze on merchant returns.
Matt Grover, director of energy markets at Fluence, told the summit that any operator running a merchant BESS would be “feeling the pinch right now” as arbitrage spreads narrow, linking the pressure directly to coal retirement timelines slipping beyond the assumptions many developers built their business cases around three years ago.
NEMPulse’s own August data showed the average daily price spread across the NEM’s five regions fell 27% month-on-month to AU$110/MWh, then held broadly flat into the September quarter at AU$126/MWh, well below the volatility that some earlier business cases had assumed.
That compression is reshaping how storage assets are contracted and financed. Thomas Dargue, director for energy markets and origination at Eku Energy, told the same summit that battery storage contracts have moved away from fixed physical tolls toward more commoditised, interchangeable products, widening the pool of counterparties willing to buy long-term capacity.
Sally Torgoman, CEO of Ascera Energy, said investor return expectations have risen alongside that shift, with projects that might previously have cleared at 8-10% returns now facing 13-14% hurdles from investors, partly reflecting the higher cost of debt.
Meanwhile, Jeremy Lloyd of Neoen told the summit that FCAS values specifically have declined sharply as more capacity has entered the market, a dynamic Kashish Shah, senior strategy lead at Wärtsilä, separately described to ESN Premium as the FCAS market having “completely collapsed” as a revenue driver, leaving energy arbitrage as the dominant source of battery revenue nationally, a shift reflected in Q3’s 97% arbitrage share.
Never miss an Australian energy storage story. Sign up for our Australia newsletter and get the latest project announcements, policy updates and market analysis delivered directly to you.