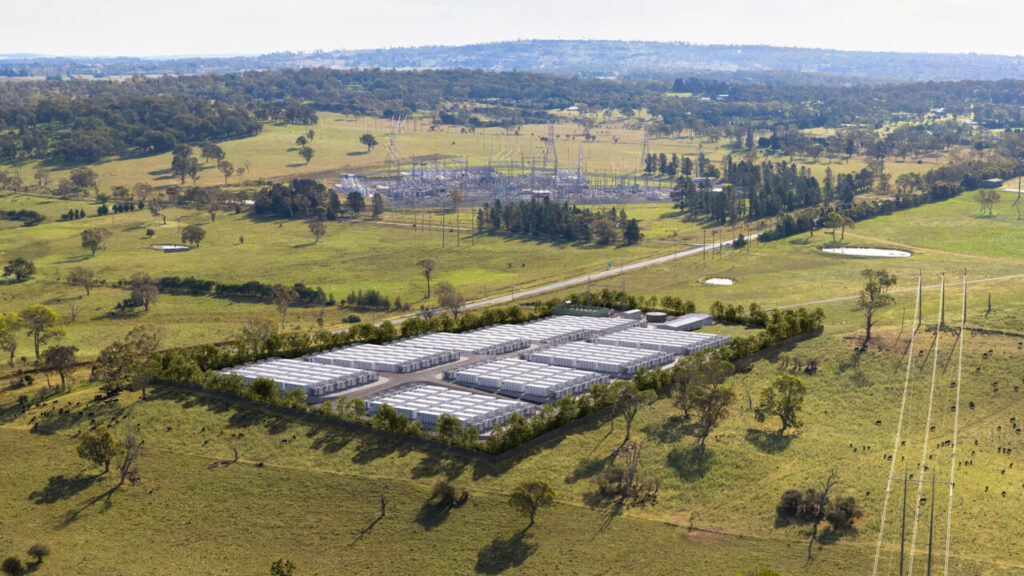
Eku Energy’s Elias Saba discusses why he believes the CIS has not fundamentally changed the company’s investment approach, argues that bidding discipline matters more than aggressive tender pricing and lays out why private offtakes remain the underpinning of Eku Energy’s Australian commercialisation strategy.
The Capacity Investment Scheme (CIS) has helped accelerate investment in longer-duration battery storage assets in Australia but has not fundamentally changed how Eku Energy evaluates and executes its own projects.
This is according to Elias Saba, chief commercial officer at battery storage developer, owner and operator Eku Energy, speaking to ESN Premium after a panel discussion at the Battery Asset Management Summit Australia 2026 saw several panellists question whether the CIS is delivering the volume of projects it was designed to unlock.
Asked whether the scheme has genuinely shifted the company’s investment decisions, Saba says the counterfactual is difficult to establish with certainty.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
“It’s always hard to know what the counterfactual would have been,” he says.
“Would we have been able to commercialise and find the right level of offtake pricing, for example, that gets the project across the line without the CIS? Hard to know, because we’re in a world with CIS, and so there is obviously an adjustment to everyone’s expectations around price based on that.”
He argues the scheme’s clearest impact has been on 4-hour duration assets specifically, a category that has taken longer to find offtakers willing to value the full duration commercially.
“I think the CIS has played a role in helping expedite some of the investment,” he says.
Bidding discipline over aggressive tender pricing
Saba pushes back on the suggestion that reliance on the CIS has slowed project delivery industry-wide, at least for Eku Energy’s own approach.
“We aren’t solely relying on the CIS close of a project, which means we need to continue to commercialise our projects with private offtake, whatever other commercialisation pathway we choose,” he says.
In his view, the fundamentals of getting a project to financial close remain unchanged regardless of whether a CIS contract is involved.
“Do you have all your planning in place? Are your grid connection works and timing falling into place as well? Are your alternatives and the required commercialisation and contracts to close in place and available?” he says.
“I don’t think the CIS has been to the detriment of the market.”
In response to criticism that CIS tenders have encouraged overly aggressive bidding, with some developers betting on winning rather than pricing a realistic path to financial close, Saba says Eku Energy has maintained a consistent approach regardless of scheme maturity.
“From the equity perspective, we’re quite disciplined in how we participate in any scheme, so we only participate in the way that we think we can deliver,” he says.
He acknowledges the company may have missed out on some tender rounds as a result, but frames that as an acceptable trade-off.
“Maybe we could have been cleared in more rounds, but it’s again hard to tell. We don’t know how aggressively others have been bidding or not bidding,” he says, adding that the same discipline applies to “any kind of tender we bid into anywhere around the world.”
That commercialisation discipline echoes comments Saba made in an earlier interview with ESN Premium, in which he attributed the shift toward longer-duration BESS assets in the NEM to a combination of falling lithium costs, improving energy density and rising offtaker appetite for the flexibility and hedging value 4-hour systems provide.
At the time, Saba said the market’s incremental storage additions were increasingly focused on shifting renewable energy generation rather than the grid stability services that dominated the earliest wave of NEM battery storage systems.
A preference for consistency over any single mechanism
Asked what Eku Energy would need from the government if the CIS were wound back or replaced, Saba resists naming a single mechanism, instead pointing to consistency as the more fundamental requirement.
“A level of consistency and stability is always key for private investment,” he says.
“The thing that I would like to see the most is just starting to have a continuous thread of activity that links from one past thread of activity to the next.”
He argues that abrupt policy shifts carry a hidden cost even when well-intentioned.
“Whenever there are drastic changes to that long-term view, it does require us to stop, re-evaluate… it does slow the velocity of investment,” he says.
That emphasis on policy consistency sits alongside a broader industry conversation about system reliability as Australia’s coal fleet continues to retire.
AEMO’s own 2026 assessment found that while the country’s overall reliability outlook has improved, continued investment in system security services will be needed as the share of inverter-based resources grows, a dynamic that shapes the kind of long-term revenue certainty developers like Eku Energy are seeking from policy settings.
Asked how the CIS compares with the mechanisms Eku Energy relies on in other markets, Saba argues that Australia’s scheme is relatively well-designed by international standards, even if not without room for improvement.
“I actually think that the CIS, in many ways, is structured well, given it’s not a structure that is easy to put together in a way that actually meets everybody’s requirements,” he says.
He points to the UK, Japan and Germany as markets pursuing similar storage incentives, without identifying a clearly superior model Australia should adopt.
“I don’t think that there’s a shining light contract that’s so much better than the CIS that we would need to adopt that structure and bring it to Australia,” he says, attributing part of the CIS’s relative maturity to Australia having iterated through more contract structures over time.
He also notes that market-specific differences limit direct transferability between jurisdictions.
“The structures that work in the UK and the structures that work in Japan for us may not necessarily make sense as structures that will work in Australia, just given the unique nature of the Australian spot market,” he says.
Private offtakes remain the underpinning commercialisation pathway
On where Eku Energy is actually finding revenue certainty amid ongoing CIS uncertainty, Saba describes a layered commercialisation approach anchored in private contracts rather than any single mechanism.
“The main underpinning commercialisation pathway for us remains private offtakes, so bilateral offtakes with partners across the range of different offtakers that we work with in the market,” he says.
Government contracts, network service agreements and a degree of merchant exposure are added on top of that base, in his account, rather than serving as primary revenue drivers.
“Everything else is fundamentally, I would say, additional, that we like to layer on to get the project to work in its totality,” he says, noting that heavy reliance on merchant exposure sits uneasily with Eku Energy’s investment approach.
“We develop infrastructure-like assets or infrastructure-like returns effectively as much as possible, and that requires an underpinning of offtakes.”
That framing is consistent with comments from Eku Energy CEO Daniel Burrows, who has separately discussed the company’s approach to attracting infrastructure capital into large-scale battery storage.
Never miss an Australian energy storage story. Sign up for our Australia newsletter and get the latest project announcements, policy updates and market analysis delivered directly to you.