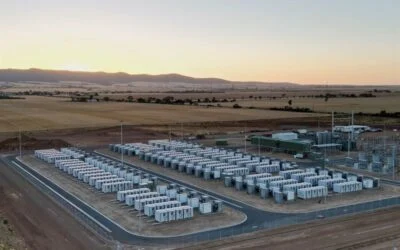
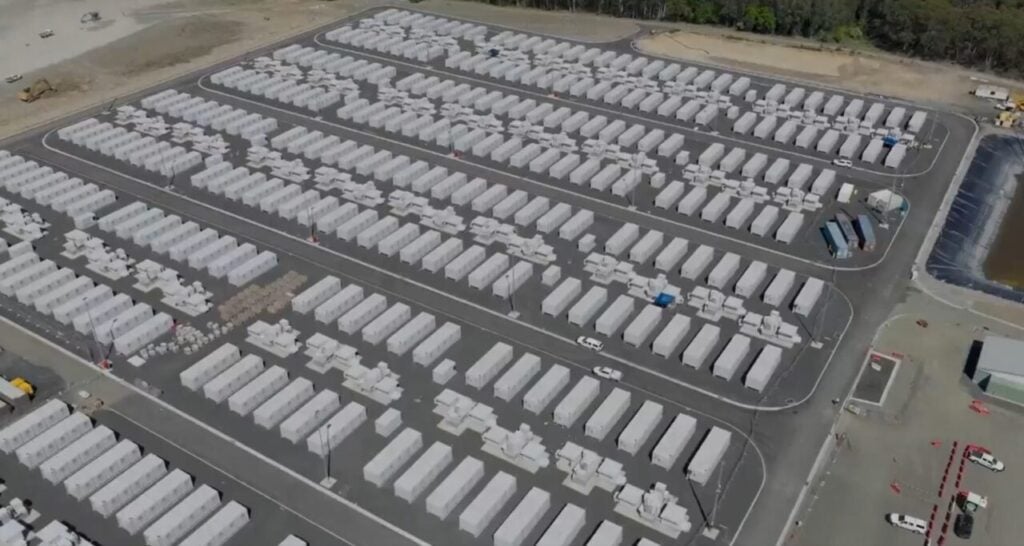
Australia’s 55 grid-scale battery energy storage systems (BESS) tracked by NEMPulse generated a combined AU$17.98 million (US$12.43 million) in estimated gross energy and frequency control ancillary services (FCAS) market revenue during June 2026.
NEMPulse is an independent, open-data dashboard that tracks the dispatch, revenue, and bidding behaviour of every grid-scale battery storage system in the National Electricity Market (NEM).
Normalised across the fleet’s 7,960MW and 18,961MWh of active capacity, battery storage systems earned AU$2,000 per MW and AU$948 per MWh for the period, equivalent to AU$27,000 per MW annualised.
Revenue per MW varied by duration class: 1-hour BESS earned AU$3,000/MW, 2-hour systems AU$2,000/MW, 3-hour systems AU$1,000/MW, and 4-hour-plus assets AU$3,000/MW.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
NEMPulse noted that longer-duration assets typically earn more per MW through energy arbitrage, while shorter-duration battery storage systems often lead on a per-MWh basis.
On energy arbitrage specifically, the fleet captured 32% of the revenue a perfect-foresight strategy would have earned over the same period, leaving an estimated AU$34.90 million on the table.
That 32% optimal capture figure reflects the difficulty of predicting exactly when and how much to discharge in real time, given the uncertainty around price spikes, state-of-charge management decisions made hours in advance, and competing FCAS obligations.
In a recent interview with ESN Premium, OptiGrid CEO Sahand Karimi highlighted that, when analysing the SA1 price event on 21 June in South Australia, the gap between what is theoretically achievable and what is captured in practice stems from forecasting, bid structure, and state-of-charge decisions made well before a price spike arrives.
“Some decisions look obvious after the event. They rarely are in real time,” Karimi said.
The three top-earning battery storage systems during June were Origin Energy’s 460MW/1,770MWh Eraring Stage One BESS at AU$1.41 million, Quinbrook Infrastructure Partners’ 260MW/619MWh Supernode Stage One BESS at AU$1.22 million and Epic Energy’s 100MW/200MWh Mannum BESS at AU$1.16 million.
Mannum’s performance is consistent with its showing during the SA1 price cap event on 21 June, when it was the top-earning battery storage system in the state with an estimated AU$151,740 in revenue during the two-hour 35-minute event alone, discharging from 21.4% to 3.2% state of charge at an average of 15MW.
Alongside the 55 grid-scale battery storage systems, 16 residential virtual power plant (VPP) and demand-response aggregator units contributed an estimated AU$13,000 in FCAS market revenue during June, at AU$214 per MW of registered FCAS capacity.
For readers unaware, VPPs participate exclusively in FCAS markets through pooled residential and commercial assets rather than in wholesale energy arbitrage.
Fleet size and revenue context
The June figures cover a fleet that is growing rapidly in installed capacity. AEMO’s 2026 Integrated System Plan, published on 25 June, confirmed that 45GW of grid-scale battery storage projects were progressing through the NEM connections process at the start of 2026, already exceeding the ISP’s own 35GW storage target for 2050.
The 7,960MW of active capacity tracked by NEMPulse in June represents the operational subset of that broader pipeline.
The pipeline contracted to the NEM also expanded during June. The Capacity Investment Scheme (CIS) Tender 8 awarded contracts to 15 battery storage projects totalling 4.2GW and 16.1GWh across New South Wales, Queensland, South Australia and Victoria, all of which are required to reach commercial operations by 31 December 2029.
Ampyr Energy, Akaysha Energy, Eku Energy, Edify Energy and Potentia Energy were among the successful developers.
The AU$17.98 million gross revenue figure carries important caveats. NEMPulse’s methodology estimates gross market revenue from energy dispatch and FCAS participation based on AEMO public data and explicitly excludes contracts, hedges, and network support schemes such as the System Integrity Protection Scheme.
Actual commercial revenue for individual assets will differ from the gross market figures depending on each project’s contracted position, operational costs and any government revenue support mechanisms such as Long-Term Energy Service Agreements or Capacity Investment Scheme (LTESA) contracts.
The per-MW figures are therefore most useful as a comparative benchmark across the fleet rather than as a proxy for project-level financial performance.
Our publisher, Solar Media (part of Informa Group), will host the Battery Asset Management Summit Australia 2026 on 25-26 August at Amora Hotel Jamison in Sydney. You can find out more about the Summit on the official website.