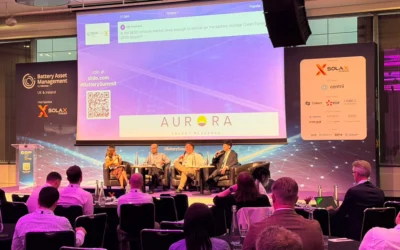
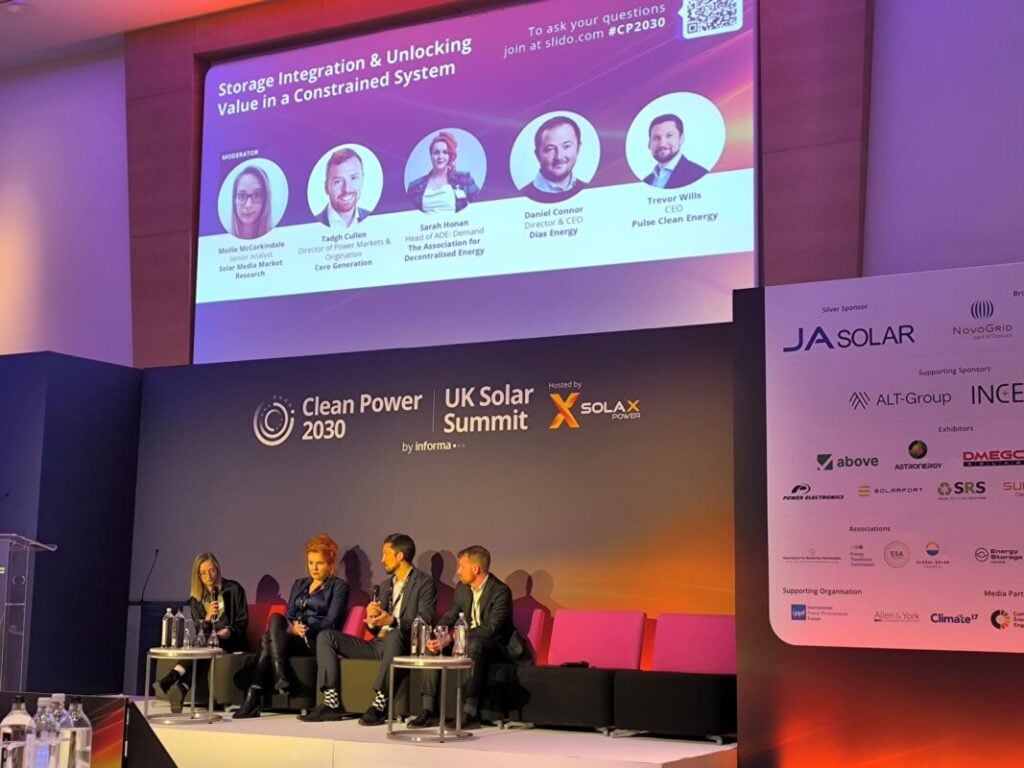
A lot of work and thought still needs to go into maximising the potential for co-location of solar and BESS technology, panellists at the Clean Power 2030 Summit said yesterday (30 June).
In a panel discussion on storage integration and unlocking its value in a constrained grid, the panel’s moderator, Molly McCorkindale, senior analyst at Solar Media Market Research, asked what the low-hanging fruit solutions were that don’t require a substantial infrastructure investment, which would help reduce the UK’s constrained grid.
Trevor Wills, CEO at BESS developer and operator Pulse Clean Energy said that on the grid side, it was “enabling the distribution network operators and transmission operator to model their true capacity in a modern way.”
He added that this starts with grid code, which forces these organisations to model new capacity or new assets coming into the system with “a very defined perspective, very oversimplified assumptions”.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
Wills gave the example of how battery storage is oftentimes modelled as a generator when it can be both a generator and a load.
“The argument that we might hear from the grid in certain circumstances is that they can’t connect us because when the system is massively oversupplied, if we generated, we would create a problem. Our response is we wouldn’t, we would be absorbing some of that oversupply and actually fixing the problem that you think that we’re going to contribute to.”
To Wills’ point, Tadgh Cullen, director of power markets & origination at independent power producer (IPP) Cero Generation, explained how batteries and solar PV don’t actually compete for the same capacity on the grid.
“Our co-located projects, we effectively modelled them as the PV getting unconstrained access to the grid connection, because it makes things easier from a financing perspective and from an approvals perspective,” explained Cullen.
However, Sarah Honan, Head of ADE: Demand at trade body The Association for Decentralised Energy, argued that “it’s not just about grid code, it’s about cultural transformation.”
She added that the new National Energy System Operator’s (NESO) new regime is “incredibly liberal”.
“Ofgem’s quote was lighter on regulation, even though they were losing basically all their financial incentives over NESO, and so they have empowered NESO to be more outcome-focused, as opposed to regimented ideals.”
UK versus Europe: co-location models still lacking
When looking at what other markets are doing, Wills highlighted that Spain has moved “very quickly in terms of its co-located structure”, whereas in the UK, most of the projects have secured a CfD and the battery operates around that profile.
“To get a new project now to financial close, what we’re seeing is we’re not actually structuring the projects as we would in the UK. You’re structuring it as a proper co-located project with one revenue contract where the battery is actually taking that generation from the PV and moving it to a time of the day when it’s actually needed.”
He added that although this sounds easy and has been the way batteries have been operating over the last 10-15 years, the reality is that they don’t work like that in the UK adding that how these projects are structured in Spain would potentially be a better way of structuring projects.
“It would open up questions like ‘should we be looking at the CfD and trying to incentivise better co-location, because I’ve never seen a policy in the UK that actually makes me think that the benefits of co-location and battery storage, in particular, are understood,” said Wills.
Cullen added that he doesn’t see any market doing it really well, emphasising that the UK was “doing a lot of right, but there’s always room to improve.”
He also highlighted the example of Italy and its schemes for storage and solar PV and how Fer X is great for a project’s bankability and getting solar PV built, while MACSE gets standalone BESS built.
“But again, there’s no thought put around actually putting those two technologies together and not competing with them against each other.”