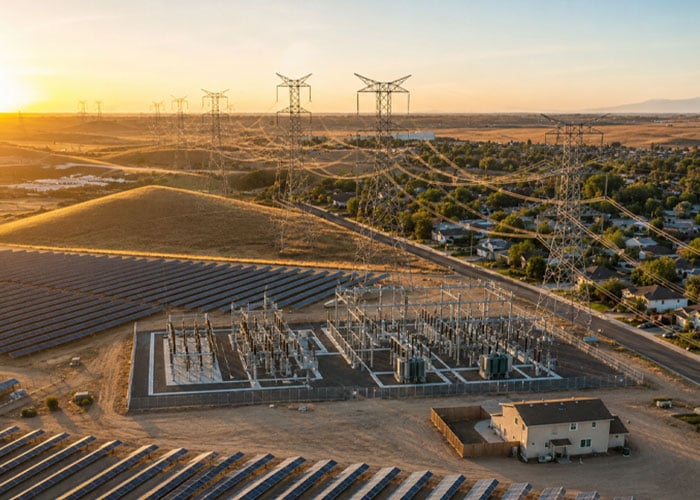
Energy-Storage.news hears the perspectives of Ateesh Samant, COO at independent power producer (IPP) Oyster Renewable, as renewables and energy storage take centre stage in India’s economic and industrial competitiveness.
In this exclusive interview, Samant offers his take on diverse topics in a rapidly-evolving market landscape. He will be speaking at this week’s Energy Storage Summit India 2026, taking place 22–24 October 2026 at the India Expo Mart in Greater Noida, Delhi NCR. See below for more details on the event, including an exclusive discount code for Energy-Storage.news readers.*
India’s energy storage market is gaining momentum as the country steps up efforts to integrate renewable energy, strengthen grid flexibility and meet rising electricity demand. However, translating awarded tenders into operational assets, scaling domestic manufacturing and establishing viable long-term revenue models remain key challenges for the sector.
In this Q&A, Samant discusses the major developments shaping India’s BESS market, including supply chain localisation, manufacturing capabilities and the opportunities and barriers to scaling battery storage deployment.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
Energy-Storage News: How would you characterise India’s BESS market compared with more established international markets, and what needs to happen for it to scale?
Ateesh Samant: India’s battery storage market is scaling fast, but on a different model from mature markets. In the US, UK and Australia, storage projects stack revenues from energy arbitrage, frequency response and capacity payments. India’s market is still largely tender-led, built on fixed-tariff contracts and supported by viability gap funding (VGF). The CEA estimates India will need 236GWh of storage by 2031-32.
Reaching that scale will require ancillary services markets and time-of-day pricing that let storage earn on the value it provides to the grid, along with bankable contracts and tighter integration of generation, storage and transmission. For developers, the real measure of progress is commissioned capacity, not capacity on paper.
What are the biggest barriers preventing awarded BESS tenders from becoming operational projects in India?
The two biggest barriers are aggressive bidding and underpriced degradation risk. Standalone storage tariffs fell sharply through 2025, reaching as low as INR148,000/MW/month for 2-hour systems, and independent analysts have flagged concerns over their viability. Bids at these levels often leave too little headroom for battery augmentation, replacement and the performance guarantees these contracts demand, which makes projects harder to finance and slower to build.
The result is a wide gap between awards and assets: India tendered about 102GWh of storage in 2025, yet installed grid-scale battery capacity stood at only around 1.8GWh by March 2026. Delays in connectivity and in signing purchase agreements widen that gap further. Bids that reflect realistic lifecycle costs, and contracts with clear accountability on all sides, will do more to convert awards into operating assets than tender volumes alone.
How is BESS changing IPPs’ long-term growth strategies, particularly in delivering round-the-clock renewable energy and improving revenue certainty?
For IPPs, storage marks a shift from selling renewable energy when it is generated to supplying it when consumers need it. That matters most for commercial and industrial buyers. Companies with RE100 and net-zero commitments are moving from annual green energy targets towards hourly matching, and exporters face growing scrutiny of the carbon content of the power they use. Wind-solar hybrids paired with storage are how developers can meet that demand.
At Oyster Renewables, round-the-clock (RTC) renewable supply for C&I customers is central to our long-term strategy. The value of storage ultimately depends on project economics, dispatch requirements and how the power supply agreement allocates risk.
How are IPPs balancing battery procurement costs, performance, bankability and the risks of relying on imported battery cells?
Battery procurement cannot be judged on upfront cost alone. IPPs need to evaluate lifecycle performance, degradation, round-trip efficiency, warranties, safety and the supplier’s ability to support the asset over its life. Reliance on imported cells exposes projects to currency movements, supply-chain disruptions and geopolitical risk.
We welcome the domestic cell capacity coming up under the Production Linked Incentive (PLI) scheme for Advanced Chemistry Cells, including the 10GWh tranche the Ministry of Heavy Industries tendered this year specifically for grid-scale storage, and see it as an opportunity to build a more resilient supply base. As that capacity scales with consistent quality, it will become a natural part of the sourcing mix. Until then, the approach is to diversify suppliers, secure strong contractual protections and evaluate total cost of ownership. For an IPP, the priority is reliable performance across the project lifecycle.
How can India build a more self-reliant domestic battery supply chain, and what is a realistic timeline for reducing import dependence without compromising competitiveness?
A self-reliant battery supply chain needs more than assembly capacity. India has to build depth across cell manufacturing, cathode and anode materials, components and technology. The country’s solar manufacturing journey offers a useful precedent: module capacity scaled quickly, while cells and upstream materials have taken longer. Storage is likely to follow a similar path. With 40GWh of the PLI scheme’s 50GWh cell target already awarded and a further 10GWh tendered for grid-scale storage, we could see meaningful localisation of cells within the next few years, provided giga-factories commission on schedule, domestic cells match imported quality, and storage tenders create steady demand. Materials and components will take longer. The milestones to watch are commissioned cell capacity, the share of domestic cells in tendered projects, and price parity with imports. The objective should be resilience without compromising project economics.
Evolving applications, evolving requirements and emerging technologies
How should India balance short-duration and long-duration energy storage, and what role could technologies beyond lithium-ion and pumped hydro play?
Storage technology should be matched to the duration, application and economics of each project. Lithium-ion suits short-duration balancing and fast response, while pumped hydro can serve longer-duration needs where geography allows. Flow batteries, thermal storage and other technologies may also play a role as their costs come down.
Generation profile matters as much as the storage choice. Wind-solar hybrids already have a flatter output than solar alone, with wind often generating through the evening and night. That can reduce how much storage, and how long a duration, is needed to deliver round-the-clock supply, which directly improves project economics.
A technology-neutral approach will let India choose solutions on reliability, lifecycle cost and suitability rather than default to one technology everywhere.
As more BESS assets come online, how can IPPs ensure safe operations, optimise performance and revenues, and maintain the confidence of local communities?
As storage scales, safe and reliable operations will determine the confidence of utilities, investors and communities. That discipline has to start at design, with the right technology selection, thermal management, fire detection and suppression, and continuous digital monitoring built in from the outset.
Performance should be judged not only by installed capacity but by availability, efficiency and degradation over time. As we bring storage into our portfolio, we intend to apply the same standards we hold our wind-solar assets to compliance with safety norms, trained operating teams and transparent engagement with the communities around our sites. Safe operations and consistent performance are essential to establishing storage as dependable infrastructure.
What are the biggest barriers to private investment in BESS, and how should government support evolve to help the market become commercially self-sustaining?
Private investment in storage depends on predictable revenues, bankable contracts, payment security and clear risk allocation. Storage economics must account for charging costs, utilisation, degradation and augmentation alongside revenue. Viability Gap Funding (VGF – the Union government Capex support scheme) has been critical in this early phase: the two VGF tranches together support 43.2GWh of capacity, and the ISTS charge waiver for co-located storage commissioned by June 2028 further improves project economics.
The next step is to move from capital support to market design. That means markets that pay storage for the flexibility, capacity and grid services it provides. Energy Storage Obligations should be enforced through state-level plans, and time-of-day tariffs should reflect actual grid conditions. A commercially meaningful spread between peak and off-peak prices would let C&I and behind-the-meter projects become viable on their own terms.
Policy should also strengthen domestic manufacturing and supply-chain resilience, with affordable and reliable storage as the goal. Abrupt domestic-content mandates could raise project costs before local manufacturing reaches adequate scale and quality, so a phased programme for domestic value addition would serve the sector better.
Together, these measures will let storage earn on its value to the grid and become a commercially self-sustaining infrastructure asset.
The Renewable Energy India Expo and The Battery Show India will run from 22-24 October 2026 at India Expo Mart, Greater Noida, bringing together developers, utilities and global technology providers. The event is co-located with the Energy Storage Summit India, now in its second annual edition, for asset owners, developers and policymakers. *ESN readers can get a 50% discount on last-minute tickets this week: Use code ESSI50 at checkout.