ASL has set a target of 1,500MW of new firming infrastructure in New South Wales (NSW) by the end of May 2033 and opened a consultation on the tender to deliver it.
ASL is the independent Consumer Trustee under the state’s Electricity Infrastructure Investment Act 2020, meaning it runs tenders for long-term energy service agreements (LTESAs), the revenue-support contracts used under the NSW Electricity Infrastructure Roadmap.
It published its 2026 Firming Infrastructure Investment Objectives Report following a Ministerial direction issued in December 2025.
The target is the Sydney-Newcastle-Wollongong sub-region, where ASL said reliability risks are most likely to emerge, and nearby projects that are electrically connected to it.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
To qualify, projects must add net energy during periods of system stress, provide dispatchable capacity when required, and sustain delivery for at least 8 hours, ideally longer.
ASL’s consultation page notes that this differs from earlier NSW firming tenders, which focused on at least 2-hours of firming capacity.
The report said fuel-based generation, including gas, is expected to meet all three requirements, while other technologies are not excluded but must show a comparable contribution on each.
Wind or solar PV projects paired with storage are expected to compete mainly in generation and long-duration storage tenders.
Why NSW expects a firming gap in 2033-34
The shortfall stems from the expected closure of the Bayswater and Vales Point coal-fired power stations. AEMO’s 2025 Energy Security Target Monitor, which checks whether the state has enough firm capacity to meet forecast maximum summer demand with a reserve for the loss of its two largest units, showed a gap of about 1,500MW in 2033-34 in its central scenario.
ASL’s own modelling, which assumes that the generation, long-duration storage and network projects in its 2025 Infrastructure Investment Objectives report arrive on time, put the indicative gap at 435MW, with expected unserved energy of 0.003%.
The reliability standard limits expected unserved energy to 0.002% of annual demand, and a proposal from the Reliability Panel to move it to 0.003% was awaiting assessment by the Australian Energy Market Commission (AEMC) at the time of the report’s publication.
When ASL added long periods of low wind and solar output drawn from historical weather years, the gap widened to 1,705MW and expected unserved energy rose to 0.014%.
The report said the on-time case is mainly a short-duration capacity problem at peak demand, but that in harsher cases “the reliability challenge becomes an energy deficit problem”, with multi-day events and limited opportunity for storage to recharge.
ASL also tested a two-year delay to infrastructure and an accelerated coal retirement with no coal-fired generation left in NSW, and said both produced materially higher reliability risk, although the report gave no figures for either test. It added that risk is highest in winter and during periods of low renewable energy output.
AEMO’s 2026 Electricity Statement of Opportunities, published in August, showed much larger gaps: 5,635MW, including government schemes and actionable developments, and 6,270MW, including only committed and anticipated developments, equal to expected unserved energy of 0.13% and 6.17%, respectively.
The report said AEMO’s demand forecast for 2033-34 is about 7% higher than ASL’s, mainly because of data centre projections, and that its government-schemes case includes about 24% less renewable energy generation than ASL’s on-time scenario, so the results are not directly comparable.
ASL said it chose 1,500MW after weighing the modelling, the AEMO monitor results, differing long-term views on gas, and the need to maintain flexibility. The 2025 report identified about 1.6GW of new gas generation in NSW by 2040, while the 2026 Integrated System Plan from AEMO, in its Accelerated transition scenario, forecast about 4.3GW and the report said the build-out depends on network and gas pipeline capacity.
The report said a lower target would reduce near-term costs but increase exposure to delays and coal closures, while a higher one would add protection at greater cost and might not be practical to deliver.
It said 1,500MW “provides greater protection than the amount indicated under the most favourable modelling outcome” and that fuel-based generation should run only when needed to limit costs to consumers.
The report said development lead times, financing, planning approvals and construction all require action well in advance, and ASL typically identifies needs about seven years before a forecast shortfall.
The consultation to deliver the tender runs from 13 October to 4 November 2026 and covers market interest, project eligibility, merit criteria that emphasise deliverability and technical capability, and the design of the LTESA product, including its Project Development Agreement.
Responses to Questions 3 to 15 will be published and attributed unless respondents advise otherwise, while Questions 1 and 2, which cover project information, are kept commercial in confidence.
ASL said it expects the tender to open in early 2027, with an indicative size of 1,500MW, and a broader Infrastructure Investment Objectives report covering generation, long-duration storage, firming and networks is due in the second quarter of 2027.
A contingent tender is possible around 2030 if updated assessments show more firming is needed, and the report said it “does not create an automatic commitment to procure another 1,500 MW in firming capacity”.
ASL added that it could give technologies with shorter lead times a chance to participate.
You can find out more about the consultation and how to participate on ASL’s website.
Earlier firming tenders and the wider pipeline
The new target follows a firming tender that has now delivered. In September, ASL and the NSW government said all projects from the 2023 firming round were operational, delivering about 1GW and 3GWh of dispatchable capacity and more than AU$1.8 billion (US$1.26 billion) of investment.
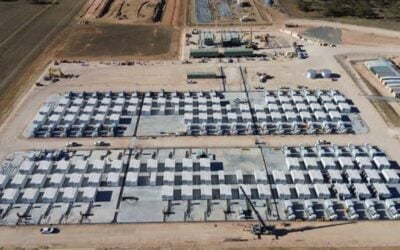
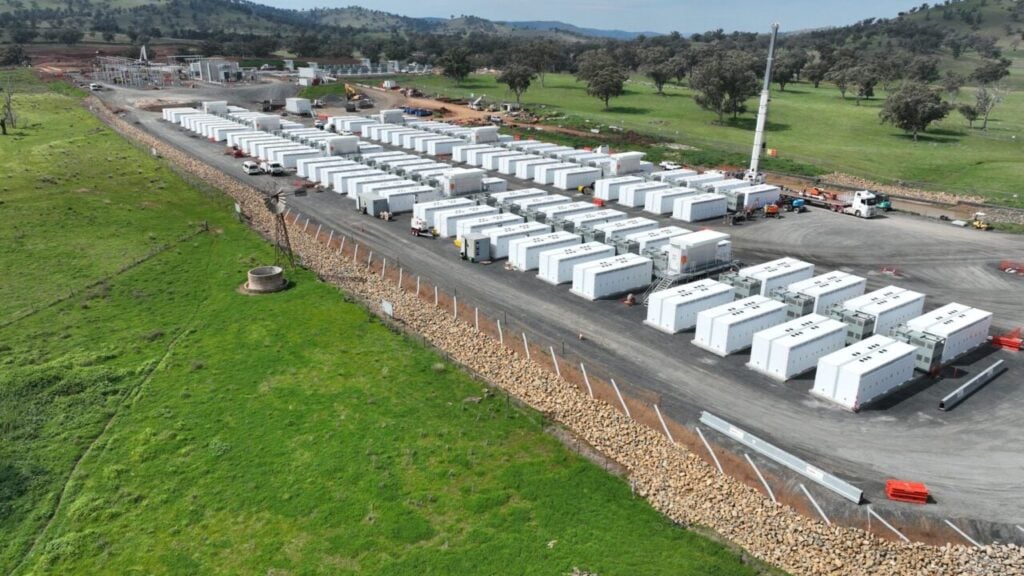
They included AGL Energy’s 500MW/1,000MWh Liddell BESS on the former Liddell coal power station site, Akaysha Energy’s 415MW/1,660MWh Orana BESS and Iberdrola Australia’s 65MW/130MWh Smithfield BESS in western Sydney.
Codevelle said at the time that LTESAs give revenue certainty through top-up payment options, and that contracted projects must be available for at least 90% of the year and respond to critical lack-of-reserve events.
The report counts firming already secured through NSW Firming Tender 7 and the federal Capacity Investment Scheme Dispatchable Tenders 3 and 8, but only shows the secured volumes in a chart.
It described the scheme, which underwrites new dispatchable capacity across the National Electricity Market (NEM), as complementary to the NSW process.
ASL is also running two larger tenders that launched in May, seeking 2.5GW of generation and 12GWh of long-duration storage. Under the storage tender, projects must maintain contracted storage of at least 8 hours over the LTESA term, and successful projects are expected to be determined in late 2026.
The report said the Roadmap sets minimum objectives of 12GW of generation by the end of 2029 and 28GWh of long-duration storage by the end of 2033, including 2GW and 16GWh by the end of 2029, but sets no minimum for firming.
How many of those contracts become operating projects is a separate question. Thimo Mueller, ASL’s general manager of commercial, told the Energy Storage Summit Australia 2026 in Sydney in March that a culture of collaboration is needed to turn awards into operating projects, with 12 of 25 LTESA-supported projects past financial close at the time.
Mueller said: “The fact that a project has an LTESA doesn’t mean it will achieve commercial operation.”
He said the LTESA addresses revenue risk but not the many other development challenges.
Never miss an Australian energy storage story. Sign up for our Australia newsletter and get the latest project announcements, policy updates and market analysis delivered directly to you.