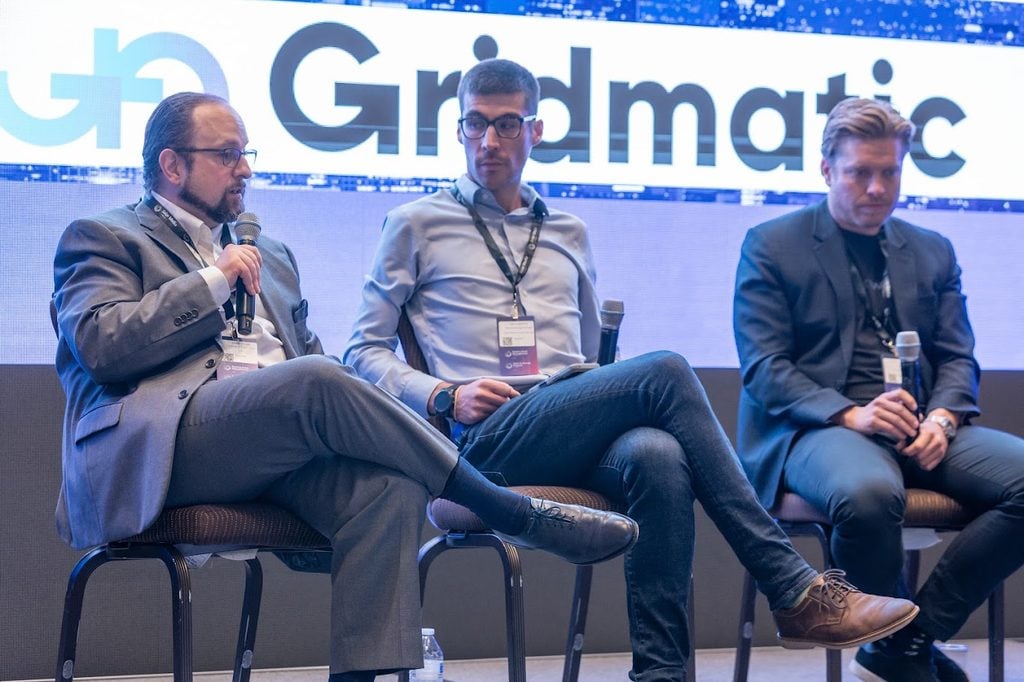
Shawn Shaw, founder and CEO of advisors Camelot Energy Group speaks with Energy-Storage.news Premium at the 2026 US Battery Asset Management Summit in Garden Grove, California.
In the wide-ranging conversation, Shaw starts off by describing the year-end rush as a perennial challenge for the battery energy storage system (BESS) sector in the US.
With equipment manufacturers and energy management system (EMS) vendors stretched thin as projects compete for limited commissioning resources, the final months of the year represent a particularly stressful period for the industry, with developers racing to meet placed-in-service deadlines while navigating an increasingly complex policy landscape.
“There’s always a scramble to place systems in service,” Shaw says. “Hybrid projects are particularly hard because people have a relatively good idea how to put solar online and complete witness testing, but this is really the time of year where the EMS vendors are running around all over trying to commission their systems.”
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
That pressure spills over into contractual disputes, with Shaw noting that his firm gets pulled into parsing the definition of “placed in service” in a way that allows a project to meet its deadline, “even if from a conventional standpoint you look at it and go, ‘you’re not quite placed in service yet’”.
Beyond substantial completion
Much of this strain, Shaw argues, stems from a misconception that substantial completion of engineering, procurement and construction (EPC) work equates to market readiness.
“Your BESS isn’t ready to participate in a market for potentially months after substantial completion of the EPC,” he explains. “The EPC wants to get paid and get off the site and wrap up the job, but as an owner, you kind of want to keep them engaged because if you need to make some tweaks or do a few things later to facilitate the testing, etc., there’s this push and pull in the later stages.”
Most wholesale markets require testing to demonstrate capabilities such as frequency regulation, creating what Shaw characterises as a “senioritis” problem, where the EPC contractor’s attention has already shifted to the next project while the owner still needs their support.
Beyond commissioning headaches, Shaw grows increasingly concerned about how recent policy shifts reshape the industry’s development trajectory — particularly the executive order affecting bulk electricity system equipment and foreign entity of concern (FEOC) restrictions.
“We heard (at the conference that the summit) the measures affecting polysilicon, and such, are going to raise the price of utility-scale solar by US$0.04 to US$0.06-per-kWh,” Shaw says. “That’s almost double what a lot of PPAs are going for, and that’s purely import restriction and regulation.”
Restricting imports without offering viable alternatives, he argues, amounts to self-sabotage: “If we want to dampen the import of this equipment for strategic reasons or geopolitical reasons, it doesn’t work if we only do it with the stick. We need the carrot as well.”
That inconsistency, Shaw says, is precisely why manufacturers remain reluctant to invest in US facilities. “The political landscape changes so quickly and so fundamentally. We went from the Inflation Reduction Act (IRA) to the so-called one big beautiful bill (OBBA) to two bills that almost couldn’t be more in opposition to one another. How are manufacturers supposed to invest in American jobs and infrastructure in that landscape?”
While South Korea offers a route to diversify supply chains away from Chinese dominance, Shaw cautions against treating it as a complete fix. “If our goal is really to eliminate Chinese influence from our energy supply chain, buying lithium iron phosphate (LFP) cells made in South Korea isn’t going to get us there, because ultimately all the roads still lead back to chemical processing.”
He points to figures showing that more than 90% of lithium carbonate refining, active cathode material production for LFP cells, and synthetic graphite for anodes still originates in China. “Sun Tzu tells us never to fight an opponent on the battlefield of their choosing, and by trying to replicate an entire LFP supply chain that China mastered five years ago, we’re doing exactly that. We need to think ahead, think of different solutions, pursue other technologies, find our own way.”
Market design shifts in storage’s favour
Despite these policy headwinds, Shaw sees encouraging progress in market design — particularly state-level programmes that give storage projects greater revenue certainty.
He points to New York’s Index Storage Credit, and similar initiatives elsewhere, as a middle ground between full merchant exposure and the needs of more risk-averse investors. “It gives a lot more protection to the revenue. If things don’t go quite to plan, the project can still hit its economic targets.”
On the regulatory side, large-scale fire testing moves from optional to mandatory, now appearing in both NFPA 855 and UL 9540A in place of earlier installation-level protocols. “It’s gone from a nice to have or a good marketing piece to a code requirement pretty quickly,” Shaw notes.
ERCOT versus CAISO
Shaw also draws a sharp contrast between how the Electric Reliability Council of Texas (ERCOT) and the California Independent System Operator (CAISO) shape storage economics.
ERCOT’s energy-focused market lacks the structured planning found in ISO environments. “The trick is really finding the right node where there’s meaningful energy arbitrage to do, because the ancillary service market is quite shallow,” Shaw says.
He typically advises clients to treat ancillary services revenue as “gravy” rather than core economics, focusing instead on energy trading — though this creates its own problem as developers converge on the same promising nodes. “A node will pop up as being volatile and have a good pricing structure, and then a pig pile of batteries will dive in there, and sometimes the last one that goes in is not realising the economic benefits they were hoping for.”
CAISO, by contrast, actively steers battery deployment through market signals, including effective load carrying capacity mechanisms designed to incentivise longer-duration storage even before energy price signals alone would justify the investment.
Optimisation needs good data
Shaw stresses that effective battery optimisation hinges on understanding true operating costs, including the degradation impact of different use cases. “Every time you discharge the battery, there is a cost to it. Do you know what that cost is, and can you weigh it against the revenue you’re going to get?”
He gives an example of a system designed for four-hour charge-discharge cycles that runs into cooling system limitations once the client wants to add frequency regulation services. “The cooling system wasn’t designed for that full 20-hour full power operation.”
Optimisation algorithms, Shaw notes, are “only as good as the data you put into it,” and require a sophisticated grasp of different degradation mechanisms — calendar ageing affects batteries differently than cycle-based wear, while frequency regulation creates minimal energy throughput but its own distinct wear pattern.
A utility-grade cybersecurity mindset
Further, Shaw believes the solar and storage sector must adopt the rigorous cybersecurity protocols already standard among regulated utilities. “I think as an industry, we’re still acting in many ways like we are not a meaningful impact on the grid. We’re not true utility infrastructure. But we are building and operating real utility infrastructure.”
He suggests some fears may be overstated, pointing out that Chinese-manufactured networking equipment already underpins much of US infrastructure, “The firewall at the entrance to your site, if you have a utility-scale storage asset, probably comes from a Chinese company. Likewise, the network switches and all that sort of thing.”
Even so, he insists the industry must prove its systems are secure: “We need to really dot our i’s, cross our t’s and show our communities, our government, and ourselves that our systems are safe and secure.”
Community opposition
Perhaps the most pressing long-term challenge Shaw identifies is community opposition. Camelot Energy Group now tracks hundreds of moratoria across the US. “We’re rapidly reaching a point where, no matter how good the project is, if the local community won’t accept it, we don’t have a project. We’re seeing projects shut down over community opposition, even if they otherwise would have been a great project.”
He attributes much of this resistance to developers treating community engagement as a “checkbox” exercise rather than a genuine partnership. “We come into a rural community and somebody puts a battery next to my school. I see the risk as very high, whilst the benefits all go back to New York City or San Francisco or wherever the developer is from, and it doesn’t set up a good dynamic.”
To address this, Camelot holds office hours with communities and authorities having jurisdiction, aiming to provide accurate information before opposition groups or unreliable sources fill the void.
Shaw points to Canada’s approach of integrating First Nations communities as project owners as a model worth emulating. “They have real stake. They’re really involved from the beginning. It creates a much more locally rooted project.”
“We’ve got to change our industry’s relationship with communities and make development local again, and make the benefits of the batteries local,” he says. “It’s not easy. It’s got its own challenges, but if it’s going to be there for 20 or more years, that’s what we want.”