Firm Frequency Response (FFR) auction prices in the UK have hit their lowest level since 2019 as market saturation begins to take effect, market analytics platform Modo Energy said.
The firm said the auction during April saw a drop in volume requirements leading to 86% of all bidded volumes, totalling 1.59GW, being rejected in each EFA block (Electricity Forward Agreement) for May delivery.
Perhaps more significantly, the reference price for this month’s tender round is just £5.69/MW/hour, a 16% fall on April and the lowest price since Modo started collecting the data back in January 2020. Prices were above £20/MW/hour from September to November 2022.
“This is the surest sign yet that saturation is really starting to bite,” Modo commercial data analyst Shaniyaa Holness-Mckenzie said.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
The smaller volumes meant that small bids did well. The average contract size across all EFA blocks was 12MW and 1MW bids managed to secure the best prices in general, Modo added.
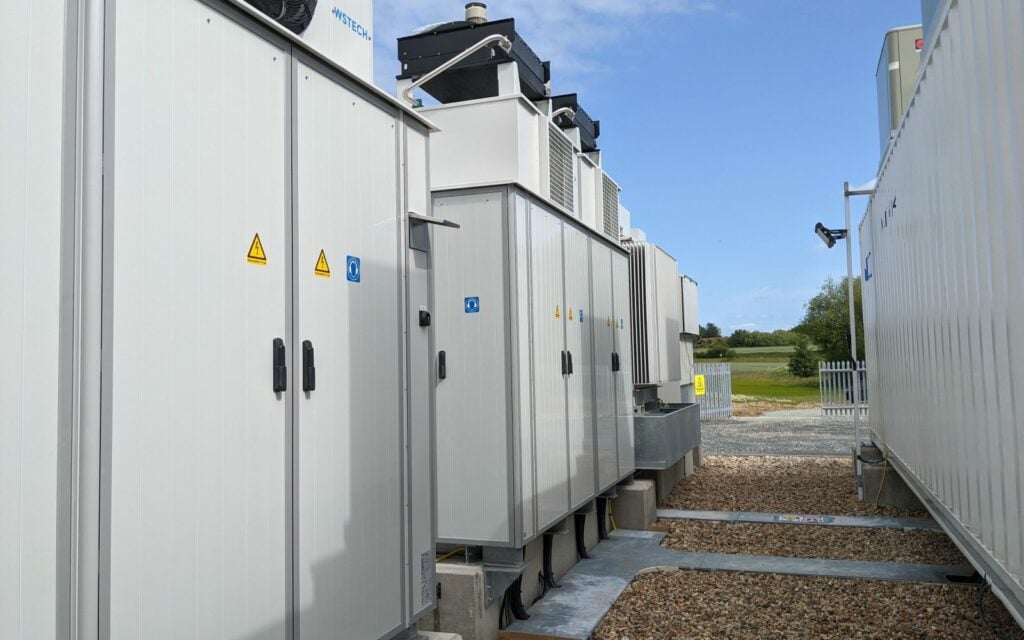
FFR is part a suite of ancillary services in the UK in which batteries make most of their revenues alongside Dynamic Containment (DC) and newer services Dynamic Moderation (DM) and Dynamic Regulation (DR). FFR is due to be retired at the end of October 2023, while the similar Enhanced Frequency Response (EFR) was retired last year.
The saturation of ancillary service markets in the UK and the shift to merchant business models based around trading energy has been expected for some time.
In an interview this time last year, Modo’s Robyn Lucas (chief analytics officer) and Alex Done (head of research) told Energy-Storage.news that they expected UK battery assets to get more of their revenues from merchant in 2022 than in 2021.
However, delays in battery storage projects coming online over 2022 meant this may not have happened as soon as expected. No new grid-scale projects came online in the UK in the four months from April to July 2022 (from Solar Media Market Research’s UK Battery Storage Project Database Report).
The largest player in the market Gresham House revealed in its annual results that trading actually fell as a percentage of revenues, from 11.5% in 2021 to 10.6% in 2022, due to “exceptionally high frequency response markets during the summer” because of said delays. FFR was 27.5% of revenues and DC 48.4%.
A similar question around market saturation of ancillary services is being discussed for the ERCOT, Texas market.