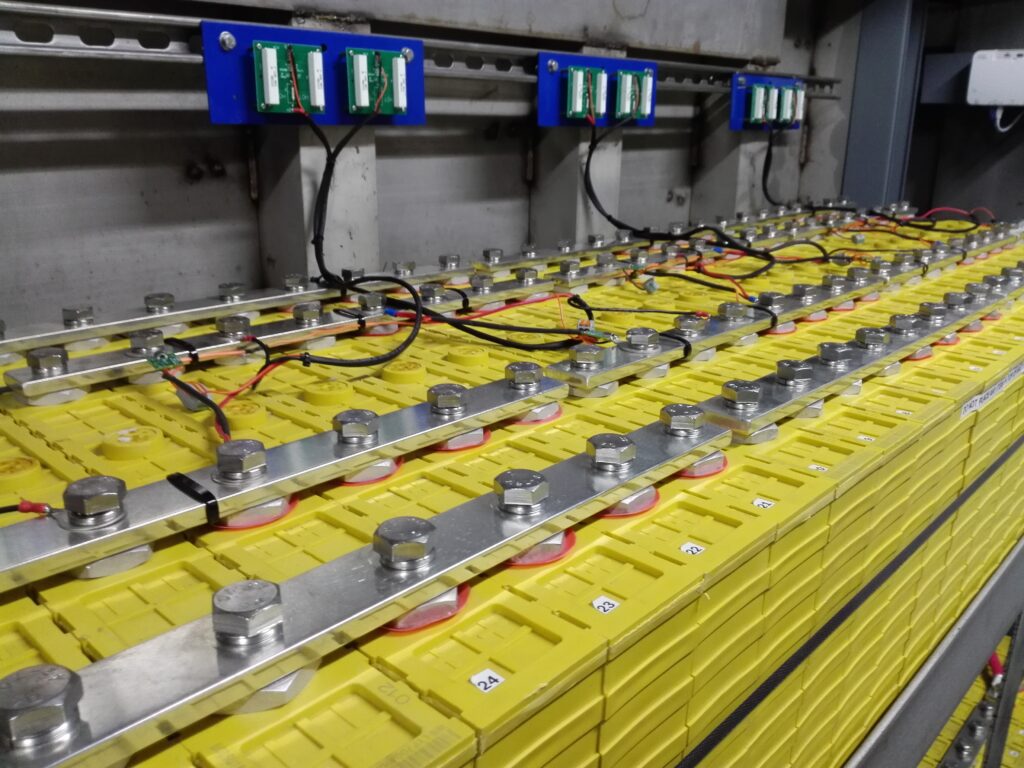
China’s share of the lithium-ion battery cell production capacity market is set to fall from 75% in 2020 to 66% in 2030 as Europe and the US ramp up domestic production, according to a new report from Clean Energy Associates (CEA).
In 2020, China accounted for 75% of the 767GWh production capacity market, the report says. In 2030, the market will be 4,764GWh and China’s market share will fall to 66% with the US and Europe muscling in at 14% and 16%, respectively, the report says.
“Europe is expected to experience the fastest growth in the cell manufacturing capacity as investment in the European battery industry is growing significantly on account of the region’s ambitious decarbonisation targets and strong demand from automakers,” it added.
The report adds that global demand for energy storage systems (ESS) will surpass 100GWh by 2025, though adds that smaller-than-expected price declines may inhibit growth.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
China and the US will be half of the global energy storage system (ESS) market over the next five years, it says.
CEA forecasts total demand for lithium-ion batteries to reach two and a half terawatts by 2030 (2,547GWh). Of this, 82% will be for electric vehicles (EVs), 13% for ESS and 4% for mobile phones or other portable devices.
“High demand from centralised PV projects is expected to increase demand for renewable energy plus storage projects, leading to strong base growth in deployment for ESS despite higher-than-expected costs potentially eroding some demand,” the report reads. The ESS sector will experience strong spillover effects from technologies designed for the EV space, it adds.
Interestingly, the report adds that lithium-ion batteries using lithium-ion phosphate (LFP) cathodes outsold those using nickel, manganese and cobalt (NMC) in China’s production market. The country deployed 100GWh of lithium-ion batteries for EVs and ESS combined, of which 44% were NMC with ‘most of the remainder’ from LFP.
NMC started the year ahead, with 5.4GWh shipped in January versus 3.3GWh for LFP, but by November LFP reached 11.6GWh, 25% higher than 9.2GWh of NMC.
“The combination of LFP’s safety advantages and increasingly lower costs as all raw material prices increase, make it a favourable solution for enetry-level EV models and stationary energy storage applications. These factors are leading to growing LFP adoption in the EV space,” the report says.
US sees lithium-ion supply chain as strategically important
Policy and funding initiatives from the EU and the US have picked up in the last few years as the two markets have sought to reduce their reliance on imports from China.
In a recent report from the Department of Energy (DoE), the US government highlighted lithium-ion batteries as an important supply chain for delivering a clean energy future, and one it could increase its market share in. It reminded readers of nearly US$7 billion of funding to address the battery supply chain including cobalt and lithium.
It also said that the US has “untapped potential to support greater domestic production” of lithium and some rare earth elements, with a significant portion of the US territory still unexplored.
Its main supply chain concerns for energy independence which related to batteries are cobalt production in the Democratic Republic of Congo and lithium and cobalt refining by China and Chinese-owned companies.